Free calculator
Debt Payoff Calculator
Compare the snowball and avalanche methods side by side. See your debt-free date, payoff order and how much interest you'll save.
Your debts
Enter APR as a number, like 22.99. Leave a row blank to skip it.
On top of your minimum payments. Even $50 makes a difference.
Your debt-free plan
Debt-free date (avalanche method)
| Method | Debt-free | Interest |
|---|
Payoff order (avalanche)
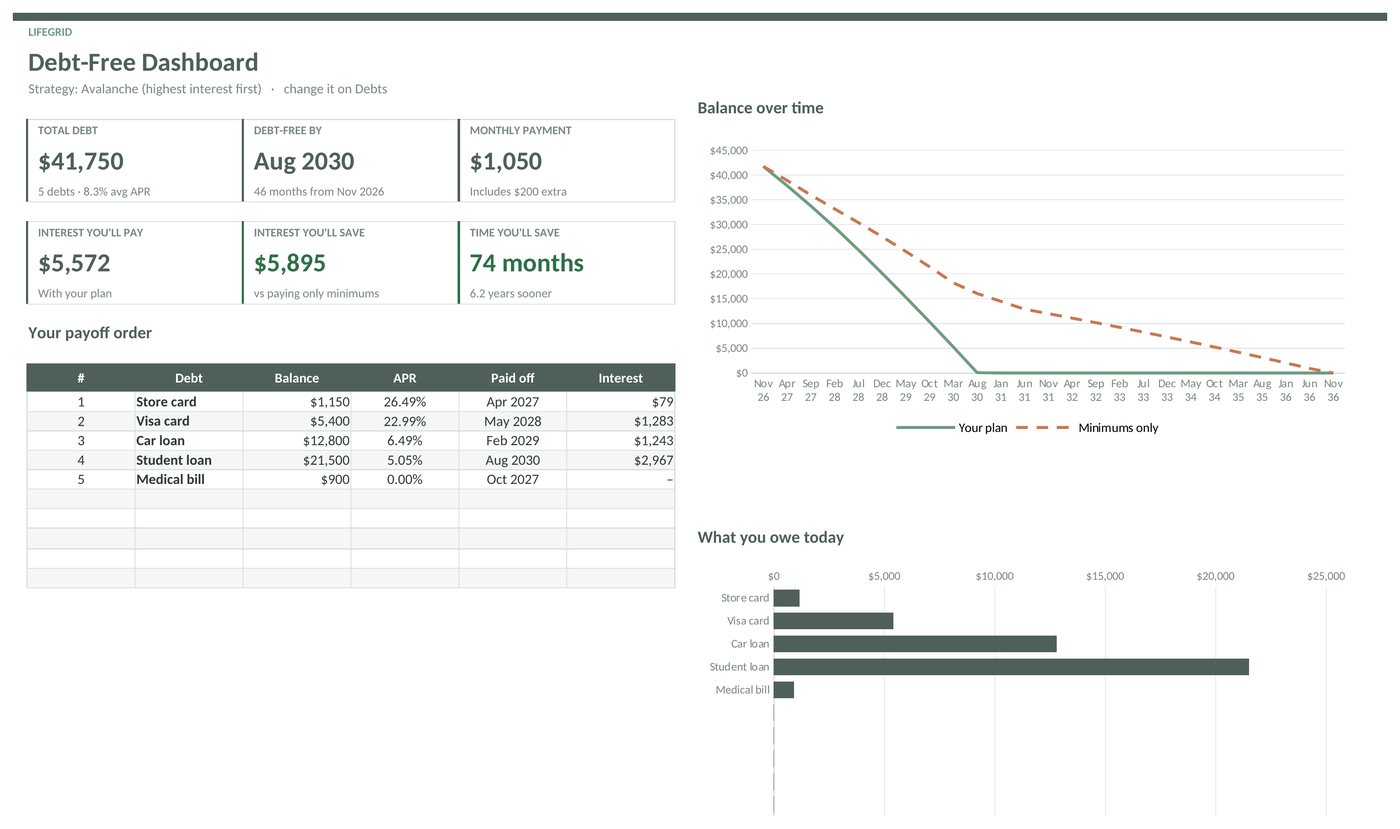
Avalanche pays the highest interest rate first and saves the most. Snowball pays the smallest balance first for quicker wins. Both roll each paid-off payment into the next debt. Assumes fixed rates and no new charges.
Save to PinterestGet your full month-by-month plan
See every payment for every debt, update balances as you go, and switch between snowball, avalanche or your own order.
- Payoff schedule for up to 30 years
- Payoff date and interest for each debt
- Flags minimums that don't cover interest
Not ready to buy?
Grab the free Monthly Expense Snapshot and see where your money went this month.
Questions
What's the difference between debt snowball and avalanche?
Avalanche pays extra toward the debt with the highest interest rate first, which usually costs the least. Snowball pays the smallest balance first, so you clear whole debts sooner. Both keep your total monthly payment the same and roll freed-up payments into the next debt.
Which method should I use?
Avalanche usually saves more interest. Snowball can feel more motivating. This calculator shows both so you can see how big the difference is for your debts.
Why does 'Minimums only' take so long?
When you pay only the minimums, much of each payment goes to interest. Adding even a small extra amount, and rolling payments forward as debts are paid off, can save years.